A Growing Unease Across Global Debt Markets
Peter Tchir, head of investment strategy at Academy Securities, has raised what he describes as a deeply concerning pattern across three pillars of the global fixed-income complex: US Treasuries, European sovereign debt, and the credit complex. According to Tchir, Thursday's price action in all three markets sharpened an unease that had been building over prior weeks.
Debt markets, he notes, form the bedrock of the entire financial architecture. When the visual, tactile, or intuitive "feel" of those markets shifts, it demands collective scrutiny. Tchir acknowledges that relying on instinct rather than a single authoritative data point may seem imprecise, yet he argues the approach is still worth pursuing.
For several weeks, his primary criticism has been directed at Treasury Secretary Scott Bessent and Federal Reserve Chair Jerome Powell (referred to in the source as "Warsh" in context) for failing to confront what he sees as the true drivers behind elevated yields. In his view, the problem is not primarily macroeconomic variables, inflation dynamics, or debates over central-bank independence. Instead, the core issue is a global oversupply of debt—spanning sovereign issuance, corporate borrowing, and, critically, the shift toward longer-duration corporate paper that has drained duration from the market.
The Treasury Paradox: Bearish Fundamentals, Bullish Positioning
Tchir's most striking observation is a paradox in US Treasury positioning. Despite a long list of fundamentally bearish factors, he claims he cannot identify a single major market participant who is aggressively short bonds. The bearish case, as he enumerates it, is extensive: crude oil and diesel prices are trending lower (a signal of weakening demand), the fiscal deficit is expanding, the long-term trajectory of aggregate debt is unsustainable, interest payments now exceed discretionary federal spending, global sovereign and corporate supply remains heavy, Saudi Arabia has shifted from being a net Treasury buyer to needing external financing for its own operations, questions persist about the dollar's reserve role, investors worldwide are rotating toward domestic-currency and corporate credit, and the Federal Reserve's independence—whether it exists or not—remains a source of uncertainty.
Tchir emphasizes that the supply story is particularly acute. He points to what he believes are back-to-back records for the largest high-yield bond issuance ever, alongside a single $10 billion corporate deal that would have drawn attention just a few years ago but now passes without comment. The duration absorption by corporate issuers, he argues, is a structural problem that neither Bessent nor the Fed has adequately addressed.
Yet positioning tells a different story. In his weekend T-Report, Tchir and his team registered a neutral stance—"Stocks plus one, The House minus one, The World question mark"—despite cataloguing additional reasons for yields to climb. He notes that across financial media, research desks, and his own investor conversations, the dominant tone is bullish or neutral. He recalls that when his team was actively bearish and challenging Bessent's policies, most of his counterparties were on the buy side of Treasuries.
One data point he finds telling: a widely shared report that a prominent bond strategist had turned bullish for the first time in six years. Tchir's interpretation is characteristically sharp—people who are genuinely short do not broadcast "buying opportunity of the decade" articles to every contact. He suspects the story was circulated by nervous long holders trying to reassure themselves, further confirming that the market is not positioned for a sustained rally in yields.
The 10-year Treasury yield's move from roughly 4.6 percent on August 25 to 5.27 percent by Friday, he says, is as noteworthy for its speed and one-directional character as for its level. He frames the situation through a contrarian lens: it is far easier to move a market against prevailing positioning than with it. If every participant were already short, pushing yields higher would require substantially more capital.
His working hypothesis involves a large pool of low-conviction long positions—traders holding Treasuries for a quick trade, asset managers slightly overweight duration versus benchmark, no single position large enough to mount a defense. In the era of electronic and algorithmic execution, true liquidity depth is thinner than the order book suggests. Most displayed bids and offers represent small, opportunistic flow rather than committed capital. Into this environment, Tchir describes "windshield-wiper" algorithms and systematic quant funds that sweep back and forth, triggering stops, adding to short positions as momentum confirms, and refusing to book profits while the trend persists. Because these participants are, by design, emotionless about direction and focus solely on whether selling begets further selling, they can amplify a move far beyond what the underlying fundamentals would justify.
Small position sizes compound the effect. A hedge fund long $100 million of 10-year notes will exit quickly; one long $10 billion might fight the move. In the current landscape, no one has the size or the conviction to push back. Momentum strategies, consistently among the top-performing approaches, are piling into the only direction that has worked—higher yields.
Tchir notes that the 20-plus-year Treasury ETF (TLT) has attracted substantial inflows, with shares outstanding at their highest level since late 2024, which aligns with the "no bears" thesis. Retail investors, he adds, have been aggressive dip-buyers in equities since the post-Liberation Day selloff, often ahead of institutional participants. He cautions against the popular narrative that "everyone is short Treasuries," calling it simply inaccurate.
European Sovereign Spreads: A Divergence That Defies Easy Explanation
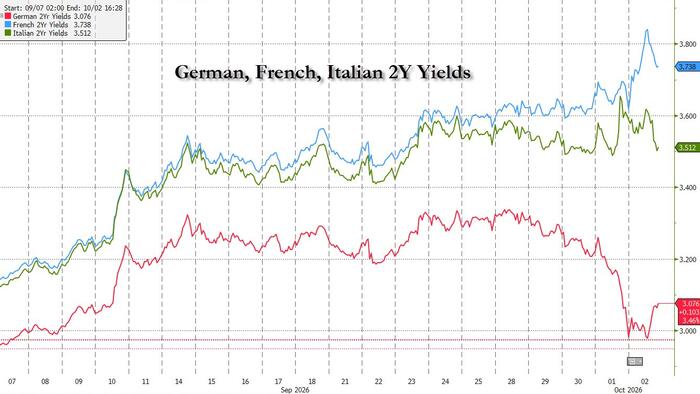
The broader rise in European bond yields, driven by increased defense and infrastructure spending, fits neatly into the global macro picture. What caught Tchir's attention is the recent divergence between German yields and those of France and Italy.
France's fiscal deficit is projected to breach the EU's 3 percent ceiling, heading toward roughly 5 percent, which explains part of the move in Paris and Rome. But the simultaneous rise in German yields is harder to rationalize. Is the market executing a genuine flight to quality within the euro area, with Germany—despite its industrial contraction and political upheaval—emerging as the perceived safe haven? Or were investors previously treating the extra yield in French and Italian paper as equivalent risk to German Bunds, only to realize the risk was not, in fact, the same, forcing an unwinding?
Tchir floats a more structural possibility: that the EU's weighted voting construct, which grants nations the size of Hungary disproportionate influence, was never designed for an era in which larger economies are moving toward vertically integrated, self-sufficient models. He references what he calls "ProSec"—a trend of major European firms prioritizing national interests—and notes that President Macron appears increasingly willing to assert a distinct European voice, citing the release of diesel from Europe's strategic petroleum reserves as a recent example.
He stops short of alarm, describing the situation as a "crack" rather than a "canyon," but insists it warrants monitoring.
Credit Signals and the Broader Risk Picture
Tchir, whose professional background is rooted in credit markets, says he has rarely needed to dust off his analytical toolkit in recent months because the sector has been uneventful. That is changing. He cites two of what he considers the largest high-yield bond deals in history, including PSKY's 8.875 percent second-lien bonds due 2034 (rated BB composite). Issued at par, the paper traded below 95 on Thursday, recovered to 96 on Friday, and closed the week at 96.5—implying a roughly $140 million mark-to-market loss on the $4 billion issuance, a hit that will sting both fast-money and long-only buyers.
One reassuring data point: the two largest high-yield ETFs, HYG and JNK, are trading at net asset value. Tchir considers any sustained discount to NAV a danger signal that can trigger a self-reinforcing selling loop, a dynamic he has previously termed the "ETF death spiral." Normal pricing in HYG, JNK, LQD (long-duration investment grade), and VCSH (short-duration credit) suggests, for now, orderly liquidity.
The CDX credit default swap index has widened from 50 to 60 over two weeks, though it remains well below the near-70 level it reached in March at the onset of the war. The Bloomberg Corporate OAS has edged up from 75 to 82 basis points over a similar window. Tchir says he is paying closer attention to the CDX because it is an observed rather than purely traded metric.
A notable dislocation: the S&P 500 posted marginal gains on Thursday and a stronger close on Friday, yet the CDX index widened on Thursday and was essentially flat on Friday. He acknowledges that "decoupling" may be too strong a word, but in the context of searching for early warning signals, the divergence is not nothing.
Volatility indicators reinforce the mixed picture. The VIX sits barely above 15, well below its 18 average for the year. The MOVE index, the bond-market analogue, stands at 107—below its March peak of 115 but well above its one-year average of 74.
Outlook: Nervous, Not Panicked
Tchir begins the new week with a neutral stance on rates, noting that fading the move worked well on Friday. But he is candid about his underlying unease. A potential Iran deal or further developments on the AI-compute front could ease tensions, but absent such catalysts, equities appear to be ignoring a growing list of fixed-income stress signals that extend well beyond the headline long-bond yield story.
He describes himself as nervous rather than frightened, and he notes with light humor that the weekend weather in the Northeast is too good to be stuck indoors writing. The broader message, however, is clear: fixed income is transmitting unsettling signals, and to the extent that market positioning does not reflect the bearish fundamentals, those signals carry the risk of amplifying into something materially larger.